Slot Farms Exploit Bingo Hall Loophole to Escape Tax
Adult gaming centres use bingo licences to avoid budget tax increases on slot machines. Discover how slot farms are skirting new gambling duty regulations.
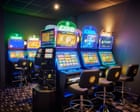
Slot Farms Exploit Regulatory Gap in Tax Framework
Hundreds of adult gaming centres operating across England's high streets are leveraging a regulatory gap that allows them to maintain discounted business rates despite facing increased gambling taxation. These establishments, commonly referred to as slot farms, continue to benefit from bingo hall licensing arrangements that provide substantial financial relief on their commercial property assessments.
The slot farms tax loophole represents a significant oversight in the government's recent fiscal policy changes. While policymakers introduced stricter regulations targeting gaming machine operations, many operators have circumvented these measures by maintaining dual licensing status, positioning themselves as bingo halls to qualify for preferential rating bands.
Understanding Adult Gaming Centres and Business Rate Structures
Adult gaming centres (AGCs) have proliferated throughout England's town centres, creating what critics describe as slot farms—establishments where gaming machines dominate the commercial offering. These venues generate substantial revenue from electronic gaming devices but operate within a regulatory framework that has become increasingly inadequate.
The business rates system traditionally allocates lower tax assessments to premises classified as bingo halls. Adult gaming centres that maintain this classification benefit from substantial discounts compared to standard retail or entertainment venues. This administrative designation, while technically legitimate, creates an unintended financial advantage that undermines recent government tax initiatives.
Recent Budget Changes and Slot Machine Taxation
Chancellor John Healey introduced significant changes to gambling taxation in his recent budget announcement. The duty levied on slot machine takings increased from 20% to 25%, representing a substantial rise in operational costs for gaming establishments. Healey framed these changes as part of a broader strategy to increase tax revenue from gambling operations, asserting that proceeds would support local business development and community revitalization across English high streets.
Despite these announced tax increases affecting slot farms and adult gaming centres, the business rates loophole continues to provide financial relief that potentially offsets taxation increases. This creates a scenario where establishments subject to higher gambling duty can partially compensate through reduced property tax assessments based on their bingo hall classification.
The Bingo Hall Licensing Strategy
The bingo hall loophole operates through a straightforward mechanism: adult gaming centres maintain bingo licences that technically qualify them for business rate discounts traditionally reserved for dedicated bingo venues. While many slot farms do offer bingo games alongside their machine offerings, the extent of this activity often appears minimal compared to gaming machine revenues.
Local authorities and tax assessors face difficulties in determining whether properties genuinely operate as bingo halls or primarily function as gaming machine venues disguised under bingo licensing arrangements. This ambiguity has allowed slot farms to continue claiming preferential business rates despite their primary revenue source being electronic gaming machines.
Government Response and Policy Implications
Policymakers must address whether the current regulatory framework adequately captures the true nature of adult gaming centre operations. The slot farms tax loophole suggests that business rates assessments may not accurately reflect contemporary gambling retail environments. Closing this gap would require either revised assessment criteria for adult gaming centres or strengthened licensing provisions that ensure business rate classifications align with actual operational characteristics.
Hundreds of establishments currently exploit this regulatory ambiguity, potentially reducing government tax revenues and creating unfair competitive advantages against genuinely diversified entertainment venues. The disconnect between gambling duty increases and business rate relief represents a policy inconsistency that stakeholders expect the government to address.
Impact on High Street Commerce
The proliferation of slot farms has become a contentious issue within urban planning and community development circles. These establishments often occupy prominent high street locations, influencing neighbourhood character and local economic dynamics. The financial incentives created by business rate discounts have accelerated the expansion of adult gaming centres, raising questions about whether tax policy inadvertently encourages their growth rather than mitigation.
Closing the bingo hall loophole could significantly affect adult gaming centre profitability and expansion strategies, potentially reshaping high street retail landscapes. However, policymakers must carefully balance such measures against legitimate business interests and established licensing frameworks.
Looking Forward: Regulatory Reform Considerations
The government faces pressure to clarify its position regarding the slot farms tax loophole and whether additional measures will accompany the recent duty increases. Stakeholders across the gambling industry, local government, and community organizations await clarification on whether business rate reforms will accompany gambling taxation changes, ensuring comprehensive policy coherence across regulatory domains.